
What this guide answers
- When does the card surcharging change take effect?
That depends on your market, and it is genuinely different from place to place.
- Are not-for-profit clubs exempt?
Rarely, and never assume it. Some markets have narrow exemptions for particular payment types or particular organisations, but "we are a not-for-profit" is not usually the deciding factor.
- Can we still offer a discount for paying by bank transfer?
Yes — a discount for one payment method is a different mechanism from a fee on another, and it stays available.
- Does this stop us charging a booking fee or a late fee?
No. This is about what may be added on top of a card payment specifically.
- What should we do about the fee line already printed on our renewal notices?
Re-issue them before the date if payment is likely to land on or after it, and keep the replacement simple: one fee, no second line, with a sentence explaining that fees now include the cost of taking payment.
USA edition. This guide is written for volunteer-run clubs in the United States. Where rules differ — grants, tax, incorporation, safeguarding — follow the USA-specific pointers below or check with your national body.
For years the small print at the bottom of a club's payment page has done a lot of quiet work: a 1.8% card fee applies. It let the committee publish a round membership number, keep the treasurer's margin intact, and put the cost of the card on the person holding it. Plenty of clubs never thought about it again.
That option is under pressure. The rules on what a merchant may put on top of a card payment have moved in market after market over the last few years, and in some places the answer is now simply that you cannot. This guide explains what has changed where you are, the things those rules deliberately do not touch, and the far better conversation they force: what does accepting money actually cost your club, and where should that cost sit?
General information only. This article is general information for community clubs, not legal or financial advice. Rules on what a merchant may add on top of a card payment differ from market to market and several have moved in recent years — some markets prohibit it outright, some cap it at what acceptance genuinely costs, and some leave it to the card networks' own rules. Before your club puts anything extra on a card payment, check your own payments regulator's current position and read your payment provider's contract, because your provider's rules bind you whatever the regulator says.
Why this guide still matters wherever you are
Even where a surcharge is available to your club, the rest of this guide is the part that pays. Most clubs that surcharge do it for one of two reasons: nobody ever worked out what card acceptance costs, or the committee wanted a headline membership figure it could keep announcing unchanged. Both are pricing problems dressed up as payment problems, and both leave the treasurer explaining an extra line at checkout to somebody who just wanted to sign their kid up for netball.
What card-fee rules usually do not touch
Wherever your rules land, they are about card payments specifically — not a general ban on every extra line a club has ever put on a price. The following normally sit outside the question altogether, but check your own rules rather than assuming:
- Weekend and public-holiday loadings. A venue or caterer that prices Sunday differently from Tuesday is doing something else entirely, and your hall-hire agreement is unaffected.
- Booking fees and service fees that apply to a transaction regardless of how it is paid. If your gala dinner ticket carries a booking fee whether it is paid by transfer or by card, that is a price, not a card fee.
- Your payment provider's own charges to you. Nothing here changes what your provider bills the club. That cost still exists — the change is about who may be asked to carry it at the moment of payment.
- Discounts. Offering a lower price for one payment method is a different mechanism from putting a fee on another, and it remains available. More on that below, including why it is not the get-out clause it first looks like.
Work out what accepting money really costs you
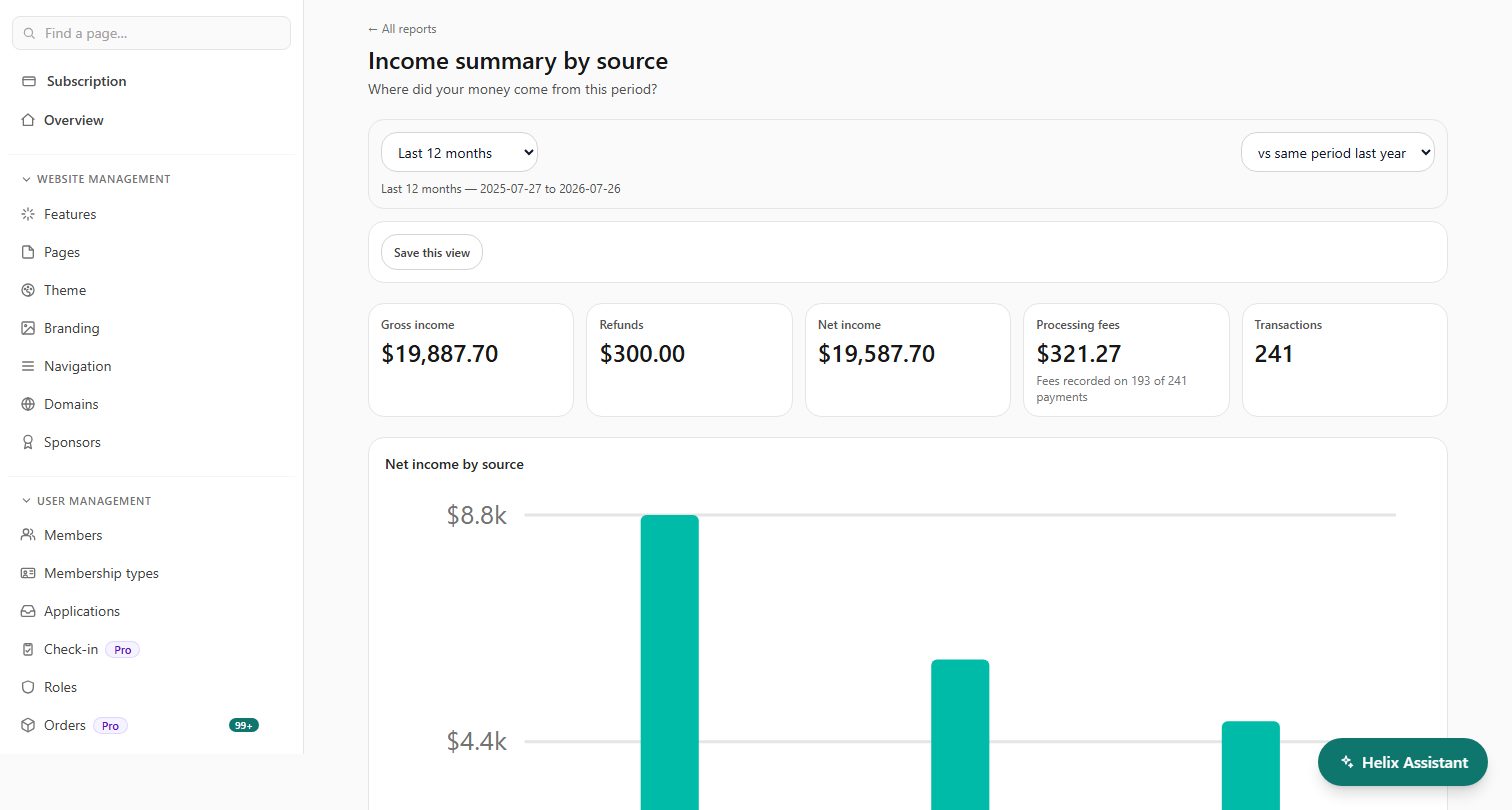
Before you change a single fee, get the real number. Not the headline rate in a sales page — the effective rate your club actually paid last season.
- Pull twelve months of payment statements. Total the fees your provider charged the club, and total the value of the payments they relate to.
- Divide one by the other. That percentage is your effective cost of acceptance, and it is almost always different from the advertised rate: fixed per-transaction components make small payments proportionally dearer, and a canteen full of small food orders has a very different effective rate from a full season fee.
- Do it per payment type. Season fees, canteen, shop orders, event tickets and facility hire will each land somewhere different. Some clubs discover that one small-value surface is carrying most of the cost.
- Add the invisible costs of the alternatives. Cash does not have a percentage, but it has a float, a count, two people in a room, a banking run, and a reconciliation session that eats a volunteer evening every month. Bank transfers look free until you price the hours spent matching "J SMITH" to the right one of three Smith families. Our cash versus card at the club canteen guide costs a full canteen day out line by line.
Now you have a number to make a decision with, rather than a feeling.
The four ways clubs cover the cost
1. Price it in. Take your effective rate, build it into the published fee, and stop talking about it.
A $300 season fee at an effective 1.8% becomes $305.40, which most clubs round to $305 or $310 — and nobody ever sees a second line.
This is where most clubs are heading, and it is the option that reads best to a family: one number, published early, the same wherever they pay it.
2. Discount another method. You can publish a lower price for the payment method that costs you least — the classic is a small discount for a bank transfer made before a cut-off. In most markets it is the one lever that stays available — check your own rules before you build a season around it, and be honest with yourselves about the trade-off: transfers move the cost rather than removing it, because somebody still has to reconcile them, chase the unreferenced ones and answer "are you sure it didn't arrive?". Many clubs that model this properly find the discount costs more in volunteer hours than the card fee did in dollars.
3. Absorb it as a cost of doing business. Put it in the budget as a line — "payment costs" — next to insurance and affiliation. That is what it is. A club that can name the number and defend it at the AGM is in far better shape than one that has been quietly recovering it at checkout and has never modelled it.
4. Reduce it. Fewer, larger payments cost less than many small ones, so an annual fee is cheaper to collect than twelve monthly ones, and a pre-ordered canteen bundle is cheaper than eight separate taps. Review the provider rate you are on, especially if your club has grown since you signed up.
Most clubs land on a blend: price the cost into big-ticket fees, absorb it on the small stuff, and review the whole thing once a year when the budget is set.
The repricing conversation, without a members' revolt
Repricing is the part committees dread, and it goes badly for exactly one reason: it arrives as a surprise in the same message as the renewal link.
Do it in this order instead.
- Decide at a meeting and minute it. "Fees for the coming season include payment costs; the card fee line is removed from all payment pages" is a one-line resolution and it protects everyone later.
- Announce it before renewals open, in its own message, with the reason stated plainly. Members are far more tolerant of a small increase they understand than a small surprise they don't.
- Say what is not changing. Concession rates, family caps, hardship arrangements and payment plans should all be named in that message, because the people who will worry most are the people already stretched.
- Use plain words. Something like: "The rules on card fees have changed, so from this season our fees include the cost of taking payment. The fee on the website is the fee — there is no extra line at checkout."
- Put the same wording everywhere. The renewal email, the registration page, the printed form on the noticeboard and the club constitution's fee schedule if it names amounts.
The repricing checklist
If you are moving a card cost into your published prices, work through this with your treasurer and whoever looks after the website:
- Remove any card-fee line from your online registration and renewal pages.
- Remove it from printed forms, flyers and the noticeboard, which outlive websites by years.
- Check your terminal settings at the canteen, bar and gate — a surcharge configured on a terminal years ago is easy to forget.
- Check your shop, ticketing and facility-hire pages, which are often set up by different volunteers at different times.
- Update fee schedules in your rules, by-laws or policies if they quote exact amounts.
- Re-check any renewal notice already issued that names a card fee, and re-issue it if payment will land on or after the change.
- Add a payment costs line to the budget so the treasurer's forecast stays honest.
- Tell your payment provider you have made the change if they ask you to confirm it.
- Brief the canteen and gate volunteers, because they are the ones who will be asked at the counter.
Where ClubHelix sits in this
Clubs collect membership fees, shop orders, event tickets, donations and facility hire through ClubHelix, with the money going into the club's own connected payment account. Two things are worth knowing while you are repricing:
- The platform fee is never surcharged to your members — what a member pays is what you published.
- Because fees are configured per membership type, per product and per booking, repricing is a settings change and a re-announcement, not a rebuild. Set the new numbers, update the copy once, and the same figures flow through registration, the shop and the public site.
If you are still collecting fees by bank transfer and a spreadsheet, this change is a decent prompt to look at the whole flow rather than just the fee line — collecting membership fees online walks through what that actually involves.
Frequently asked questions
When does the card surcharging change take effect?
That depends on your market, and it is genuinely different from place to place. Check your payments regulator's current position and your payment provider's contract before you publish a fee that sits on top of a card payment, and re-check it each season — this is an area that has moved repeatedly in recent years.
Are not-for-profit clubs exempt?
Rarely, and never assume it. Some markets have narrow exemptions for particular payment types or particular organisations, but "we are a not-for-profit" is not usually the deciding factor. Check the rules that apply where your club is, rather than reasoning from what feels fair.
Can we still offer a discount for paying by bank transfer?
Yes — a discount for one payment method is a different mechanism from a fee on another, and it stays available. Just cost it honestly before you build a season around it. Transfers arrive without a clean record of who paid, so the saving on payment costs often reappears as reconciliation work for the treasurer and chasing for the registrar. Our comparison of bank transfer versus online card payments sets the two side by side.
Does this stop us charging a booking fee or a late fee?
No. This is about what may be added on top of a card payment specifically. A booking fee, a service fee or a late fee that applies however the person pays is a price your club has set, and it sits outside this change entirely. Publish it clearly, apply it consistently, and make sure it is the same whether the payment lands by card, transfer or cash.
What should we do about the fee line already printed on our renewal notices?
Re-issue them before the date if payment is likely to land on or after it, and keep the replacement simple: one fee, no second line, with a sentence explaining that fees now include the cost of taking payment. It is far less work than answering the same question from forty families in October, and it avoids a member paying an amount your system can no longer justify collecting.
Collect fees, shop orders and bookings through your own club site with ClubHelix, and keep the money side readable with reports your treasurer can reconcile. Next: how to collect club membership fees online and tracking who has paid.


